Homeowners Insurance
Protection specifically designed for your property.
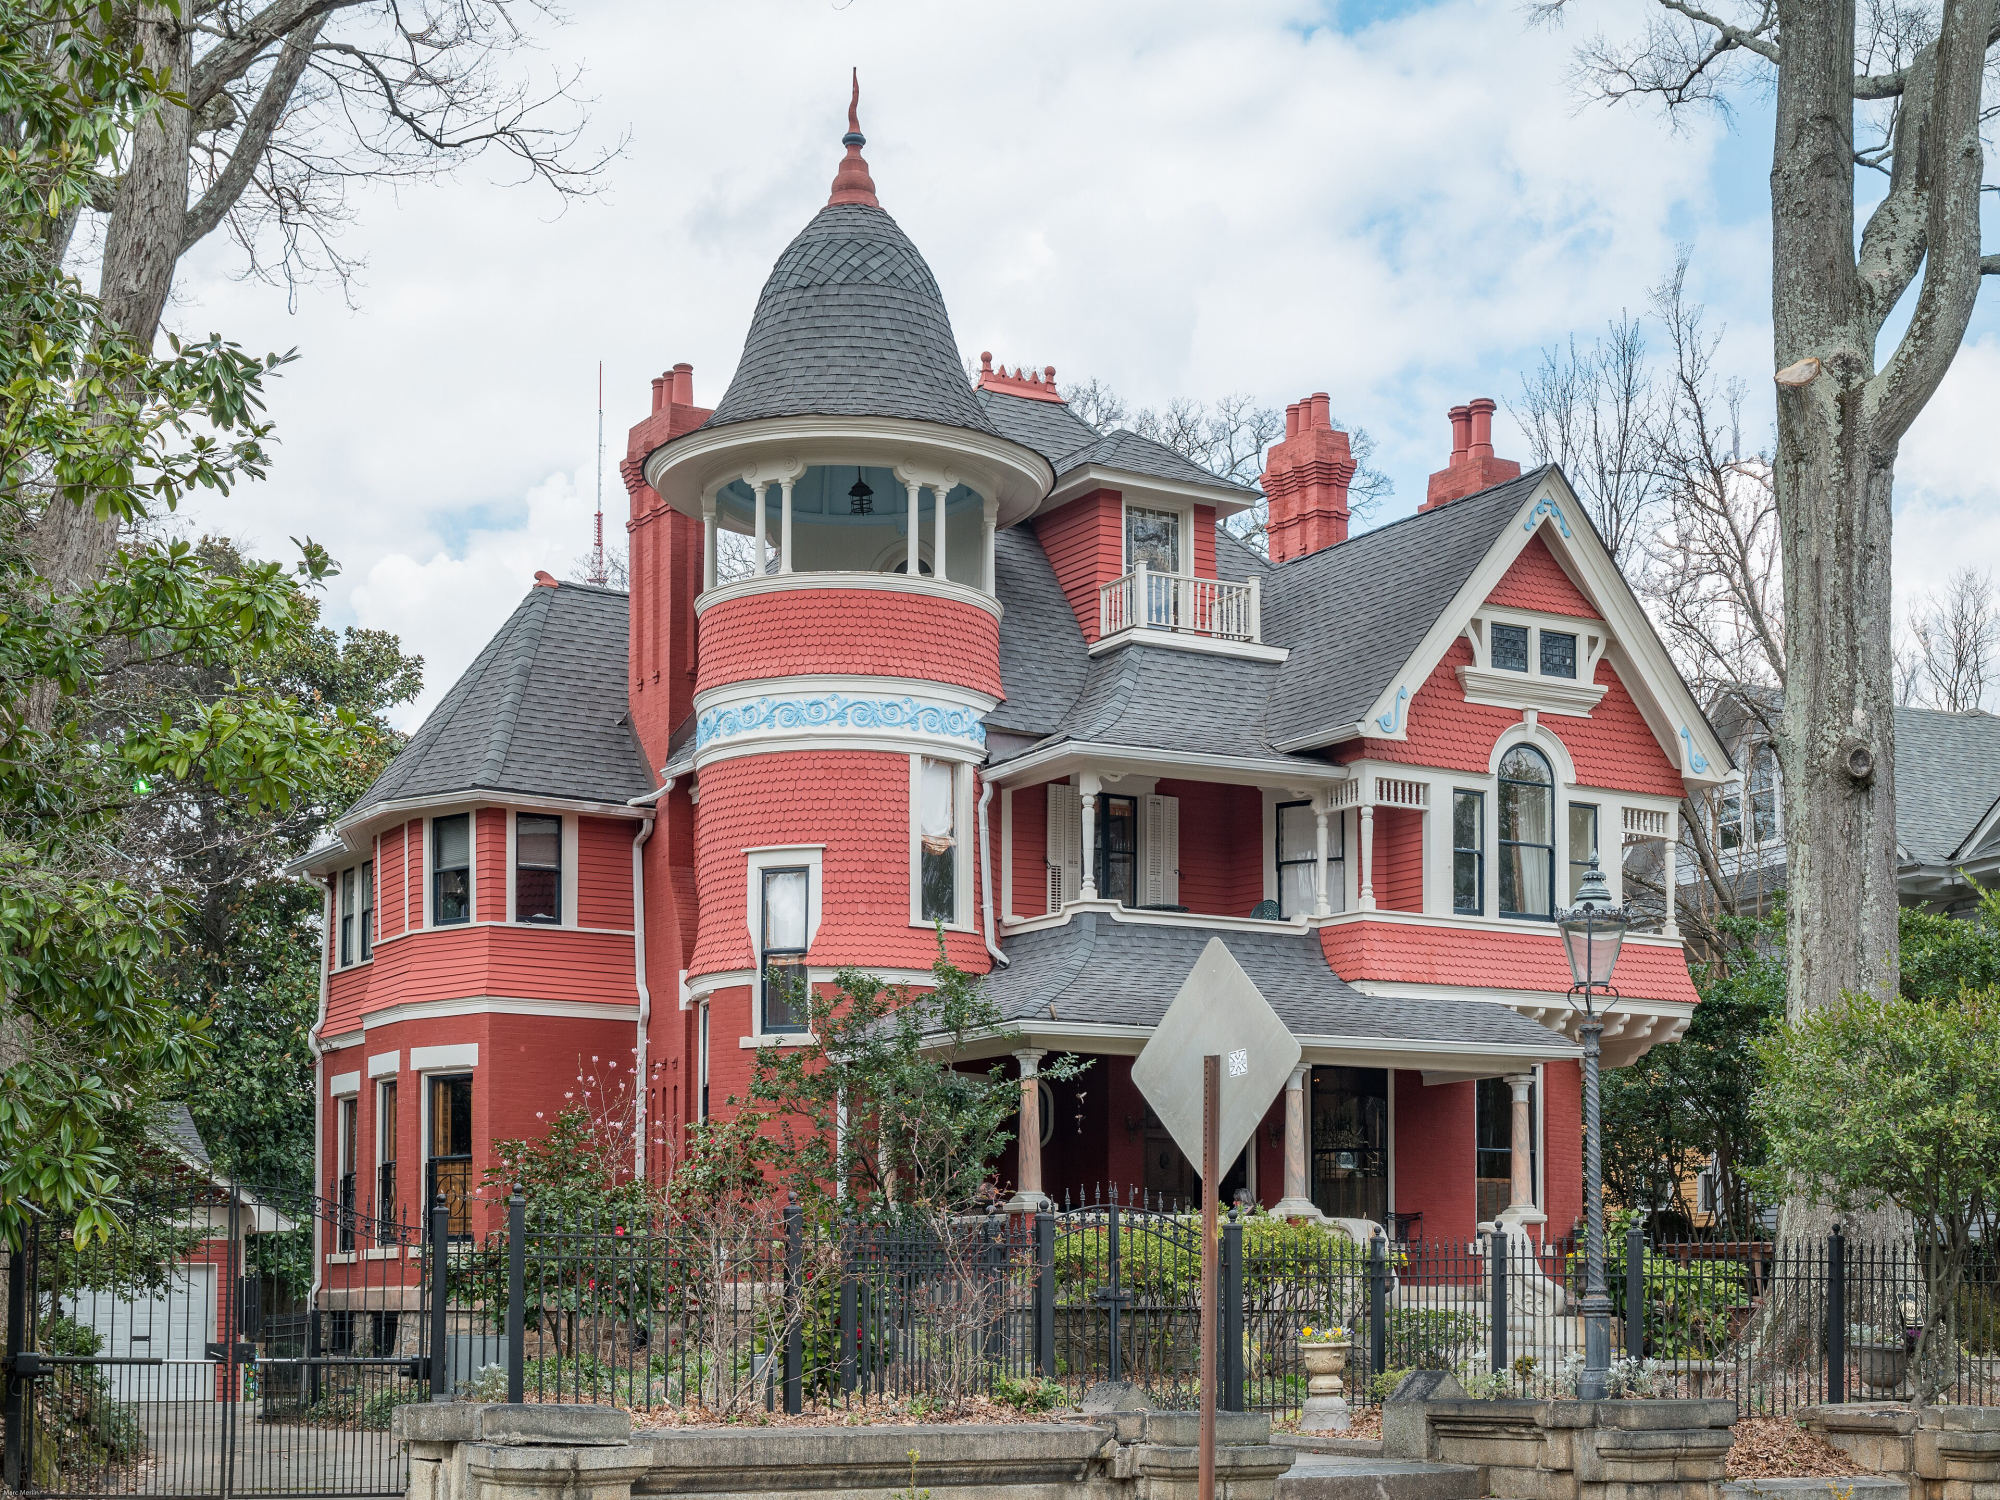
What it is
A homeowners policy covers the structure of your home, the belongings inside it, your liability if someone is hurt on the property, and the cost of living elsewhere while a covered loss is repaired. Your mortgage lender requires it; a well-built policy does more than satisfy the lender. We write it for homeowners and condominium owners across metro Atlanta and Georgia.
Why it matters
A fire, a fallen tree, a burst pipe or a liability claim can each cost more than most households keep in reserve. The policy is what stands between a bad week and a bad decade. What matters is how the dwelling limit, the deductibles and the endorsements were set before the loss, because none of them can be changed after it.
Who needs it
Anyone who owns a house or condominium in metro Atlanta or Georgia, anyone carrying a mortgage, and anyone whose current policy has not been reviewed since the home was bought.
In Georgia
Our approach is coverage first, ensuring our clients are adequately protected, and then diligently working on finding a better price. For a house, that means the dwelling limit is set to what it would cost to rebuild, not to the sale price, before the premium is compared across our carriers.
What the policy can include
- Dwelling coverage for the structure
- Other structures: detached garages, fences, sheds
- Personal property
- Loss of use and additional living expenses
- Personal liability and medical payments to others
- Scheduled personal property for jewelry and valuables
- Wind and hail deductible options
Information is general in nature and may not reflect your specific situation. Policy language, not this page, determines coverage.
Cobb County’s population estimate for July 1, 2025 was 793,345.
Source: U.S. Census Bureau QuickFacts, Cobb County, Georgia (Population estimates, July 1, 2025, V2025), read September 15, 2026.